All Categories
Featured

Navigating Medicare Part D Coverage in 2026
Table of Contents
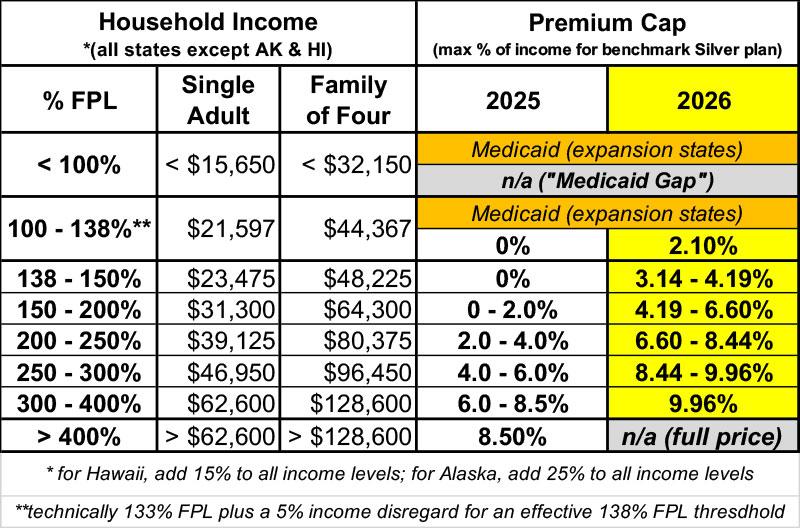
Households pick a CHIP provider throughout registration, and the carrier handles all strategy advantages, permissions, and customer service. CHIP providers are various from Pennie marketplace providers not all Pennie providers take part in CHIP. How does the 2026 aid cliff affect Pennsylvania family health insurance? The return of the 400 percent FPL subsidy cliff in 2026 approximately $128,600 annual earnings for a household of 4 significantly increased costs for middle-income Pennsylvania households on Pennie.
Even families above the APTC threshold might have kids eligible for CHIP if household income is listed below 319 percent FPL per-child, considerably minimizing total family protection cost. Can Pennsylvania households enroll in CHIP outside of open enrollment?
Children who gain eligibility due to income modifications, loss of other coverage, or other situations can be enrolled in CHIP at any point throughout the year. CHIP, Medical Assistance, and Pennie marketplace plans often collaborate for Pennsylvania families.'s licensed PA brokers verify eligibility for every family member and total enrollment at no additional expense.
is not associated with Pennie, the Pennsylvania Department of Person Providers, the Pennsylvania Insurance Coverage Department, or any carrier including CHIP providers. The firm helps Pennsylvania locals compare strategies and enroll in coverage at no additional cost.
An insurance coverage program collectively moneyed by states and the federal government that offers medical insurance to low-income kids and, in some states, pregnant women in households who earn too much earnings to receive Medicaid however can not manage to acquire personal medical insurance coverage.
Comparing Personal Health Insurance Quotes Easily
We learned yesterday that the average cost of a family medical insurance policy through a company reached nearly $27,000 this year, 6% higher than what it cost in 2024. As if that weren't alarming enough, scientists are predicting that the overall most likely will soar towards $30,000 next year since of rising medical costs and the unrelenting pressure insurers are under from Wall Street to increase their revenues.
Despite repeated guarantees from insurance providers that we can count on them to hold down the cost of health care and subsequently the premiums they charge there are now several years of proof from researchers like KFF, which tracks annual changes in employer-sponsored coverage that they have not and can not provide on their promises.
A medical insurance policy today is generally less valuable than it was a decade earlier due to the fact that families have to spend a growing number of cash out of their own pockets every year before their coverage kicks in. In addition, they are far more most likely to be alerted that their insurers will not cover the care their medical professionals say they need.
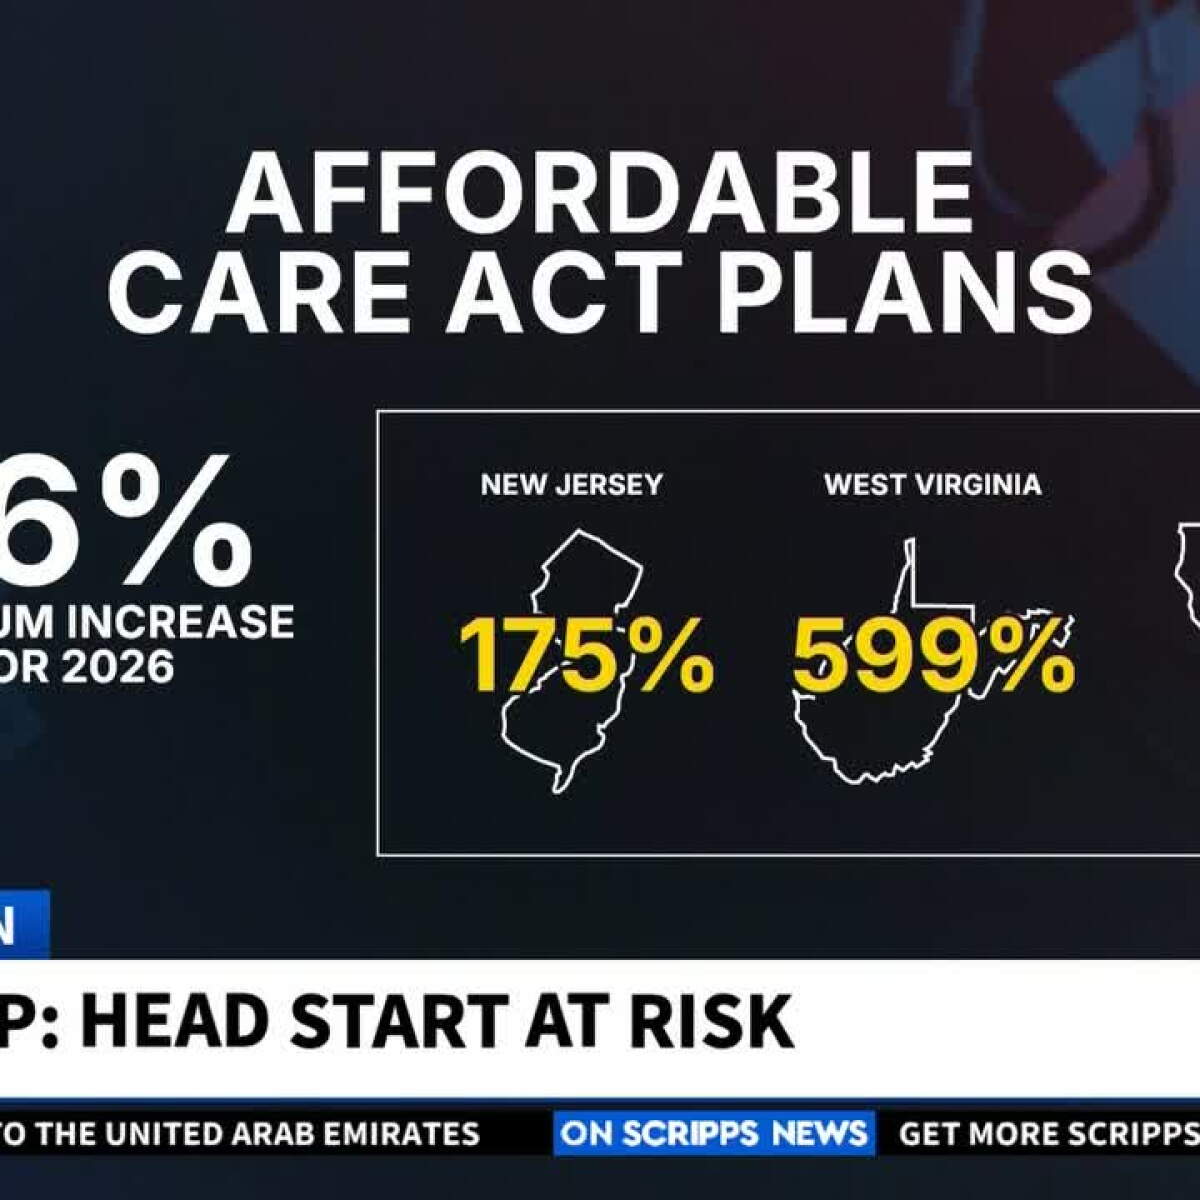
That is a rate of boost much greater than general inflation and likewise greater than medical inflation. Not just has the total expense of an employer-sponsored plan skyrocketed, so has the share of premiums employees need to pay. This year, companies subtracted an average of $6,850 from their workers' incomes for family coverage, up from $4,823 in 2014, a 42% boost.
Insurance in Chino CAThe Affordable Care Act, to its credit, set up a cap on out-of-pocket costs in 2014, but that cap has actually been increasing yearly along with premiums. (The U.S. Department of Health & Person Providers sets the out-of-pocket max every year, pegging it to the average increase in premiums.)In 2014 the out-of-pocket cap for a household policy was $12,700.
Comparing 2026 Term Life Insurance Rates for Families
And bear in mind that the cap only applies to in-network care. If you head out of your insurer's network or take a medication not covered under your policy, you can be on the hook for hundreds or thousands more. While the majority of employer-sponsored plans have caps that are substantially lower, numerous individuals and families reach the legal max every year.
Jointly, those 7 business made $71.3 billion in revenues in 2015 alone. That was up slightly from $70.7 billion in 2023. Insurance providers stated their 2024 revenues were somewhat depressed since more of their health insurance enrollees went to the medical professional and got their prescriptions in 2015. Financiers raged that insurers could not keep that from happening, as you'll see in the charts below.
But in general, the stock costs of the huge insurance coverage corporations have actually increased steadily over the years as we and our companies have needed to spend more for policies that cover less. UnitedHealth Group, the most significant of the 7, saw its stock price increase 483% in between 2014 and 2024 from $85.31 a share on Dec.
Comparing 2026 Medicare Advantage Coverage
31, 2024. Most of the other companies saw comparable growth in their shares over that time duration. By contrast, the Dow Jones Industrial Average increased 139% (from $17,823.07 to $42,544.22), and the S&P 500 increased 186% (from $2,058.90 to $5,881.63) during the exact same period. Back to those premiums and out-of-pocket requirements.

Latest Posts
Why Indexed Universal Life Builds Value
Exploring Final Expense Insurance Benefits for Veterans

Essential Part D Selection Tips in 2026